Decide whether an employee gift allowance pays for merchandise or discounts merchandise before allowing it to combine with sale prices and promo codes. Those are different checkout mechanisms. A gift-card balance used as payment can coexist with a discount even when a program owner thinks “no stacking” is enabled. A fixed-value discount used to represent an allowance can instead conflict with another promotion and disappear from the cart.
The right policy is the one that preserves the promised employee benefit, assigns the cost of promotions and produces an order record your team can explain. Do not let a retail promotion silently rewrite an employer-funded recognition program.
Publisher perspective: Brand Sauce publishes this company-store operating guide. The policy framework and test cases below are editorial recommendations, not a claim that every Brand Sauce store supports these controls. Shopify documentation illustrates specific platform behavior; verify your own configuration and request a quote for any additional implementation or service work. Sources checked October 21, 2026.
Separate price, promotion and funding
Start with three layers. The selling price describes what the item costs now. A promotion changes an eligible price or charge. Funding determines who pays the resulting amount. An employee invitation may call its benefit a gift code, but that friendly name does not tell you which layer the underlying mechanism occupies.
| Layer | Company-store example | Decision to document |
|---|---|---|
| Selling price | A sweatshirt listed at its current program price | Which price applies when the employee orders? |
| Promotion | A percentage reduction on an eligible collection | Can recognition purchases receive this reduction? |
| Funding | An employer-funded balance applied toward the order | Which charges can the employer pay, and who pays the rest? |
A reduced selling price is not necessarily a second checkout discount. If a supplier changes a product's listed price, switching off discount combinations may do nothing to exclude that price from the gift program. Conversely, a code described as a “balance” may only subtract a fixed amount once, with no separate funding record. Ask the provider to demonstrate the actual mechanism rather than approve the terminology.
The choice between a one-order allowance and a reusable balance remains important, but this guide answers a different question: what happens when a promotion meets that allowance on the same purchase?
What the platform examples establish—and what they do not
Shopify's gift-card redemption documentation says gift cards can be used with discount codes, can retain value across orders and apply to the order total, including shipping and taxes. That is a concrete reason not to treat gift-card payment as equivalent to a merchandise-only coupon. The example does not establish the terms or configuration of your employer's gift program.
For actual promotions, Shopify distinguishes product, order and shipping discounts. Eligible combinations depend on settings on each discount. Its documentation also describes selection of the better applicable discount when discounts cannot combine. Thus, rejecting a combination is not necessarily the same as prioritizing the employer's intended benefit.
Automatic discounts can apply when cart and customer eligibility conditions are met, without the recipient typing a code. Testing only a blank promo-code field misses that route. Review automatic offers alongside manually entered promotions.
Use these facts to frame the demonstration request, not to assume all stores work this way. Ask your provider to show the displayed prices, adjustment lines, funding amount, employee amount due and exported record for the exact program. If a required restriction depends on an app or custom work, establish its scope and cost before publishing the invitation.
Choose one of three promotion policies
There is no universal reason to ban or encourage stacking. Choose a policy based on the gift promise and who absorbs the discount.
| Policy | Useful when | Main tradeoff |
|---|---|---|
| Gift purchases use a dedicated program price; unrelated promotions excluded | The employer promises a defined selection with predictable funding rules | A lower public price may require explanation; exclusion must actually work. |
| Approved promotions reduce the price before funding is used | The employer wants recipients to benefit from eligible sale prices | The team must decide whether any unused allowance remains available. |
| Only named campaign combinations are permitted | A particular event includes both a merchandise benefit and a shipping offer | More combinations need ownership, testing and retirement dates. |
For a small recognition program, a dedicated eligible assortment with a short, explicit promotion policy is often easier to explain than a maze of exceptions. That is an operating recommendation, not a platform requirement. A company with an established retail-style employee shop may reasonably prefer approved promotions so employees do not lose normal shopping benefits during a recognition campaign.
Do not equate lower checkout spend with lower employer cost. A provider-funded sale, an employer-funded subsidy and a special invoice credit have different commercial effects. Require the quote or agreement to identify who funds each adjustment. If nobody can identify the sponsor of a promotion, do not build your program budget around it.
Work through one order before approving the rule
Illustrative calculation only—not Brand Sauce pricing or measured savings: suppose eligible merchandise totals $100, an approved promotion reduces it by $20, and an employee has $75 of employer funding. Assume this example excludes taxes and delivery so the funding interaction is visible.
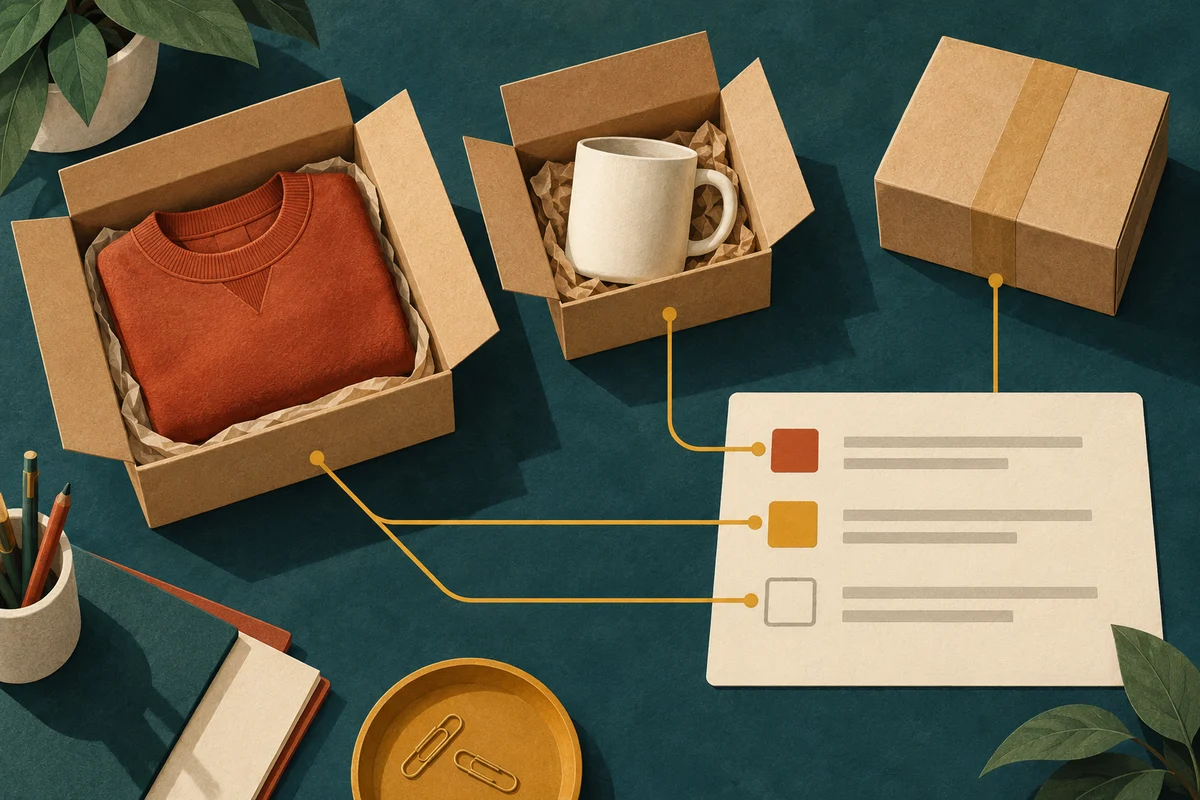
- If the promotion applies first and the allowance is funding, the merchandise amount becomes $80. Employer funding covers $75 and the employee pays $5.
- If the promotion is excluded, the merchandise amount remains $100. The same funding leaves $25 for the employee.
- If the “$75 allowance” is actually a non-combinable discount, another promotion may compete with it. The result depends on the platform's rules and configuration, not the invitation's wording.
Now change the cart to merchandise totaling $60. With a permitted $12 reduction, the purchase requires $48 before excluded charges. If the benefit is a reusable $75 funding balance, the intended remainder might be $27. If it is one complete selection with no carryover, there may be no second shopping opportunity. Write that outcome down before testing; a mathematically correct order can still violate the program promise.
Run a separate example with delivery and the applicable tax calculation shown by the actual checkout. Do not extend the simplified arithmetic into a tax rule. If employees must never pay to receive the basic gift, verify a complete, delivered, fully funded choice—not merely a product whose sticker price fits the allowance. Treat optional employee-paid upgrades as a separate decision.
Create a promotion approval record
Give every approved interaction a short record that both the program owner and store operator can read. This is a recommended specification; it need not become another software system.
- Program: occasion, eligible population and responsible owner.
- Benefit mechanism: discount, gift-card payment, account credit or another verified arrangement.
- Eligible purchase: products, variants and relevant delivery destinations.
- Allowed adjustments: current sale prices, named codes, automatic offers and shipping promotions.
- Excluded adjustments: unrelated offers and how exclusion is enforced or explained.
- Funding order: expected sequence, charges covered and permitted employee contribution.
- Remainder rule: what remains available after a discounted purchase.
- Commercial responsibility: who funds the promotion and how the invoice reflects it.
- Change control: start and end conditions, person allowed to edit the rule, and cases requiring retesting.
Keep entitlement identifiers separate from promotion identifiers. A completed order should show which gift opportunity it satisfied even if the recipient also received a sale reduction. Otherwise, a report organized only by promo code can make an employee appear not to have used the recognition benefit, inviting unnecessary support work or a duplicate grant.
Test interactions, not just a successful checkout
Use a controlled pilot or test environment supported by the provider. Agree on the expected outcome first. A tester should record what actually happened, not change the expectation afterward to match the screen.
| Test cart or journey | Question to resolve | Evidence to retain |
|---|---|---|
| Eligible full-price item with only the gift benefit | Does the baseline promise work? | Order summary and funding allocation |
| Same item with an approved code | Does the intended combination apply? | Adjustment lines and amount due |
| Same item with an automatic offer | Does an unseen promotion change the benefit? | Active offer and resulting order |
| Eligible and excluded products together | Does funding or discount spill into excluded items? | Line-level eligibility and totals |
| Gift plus an unrelated shipping code | Is the delivered amount still what was promised? | Delivery charge and payer |
| Discounted order below the allowance | Is the remainder handled correctly? | Post-order entitlement or balance |
| Assisted order entered by support | Does the alternate ordering path preserve the policy? | Same comparison fields as self-service |
Also test the transition at the end of an offer. An employee may open the invitation during a sale but finish later. Decide which message explains the current price and where support should route a disputed promise. Record the effective time zone so the campaign owner and store operator do not interpret the same end date differently.
If a failed test cannot be fixed without substantial work, simplify the approved offer or delay the affected campaign. Do not rely on support to manually repair every ambiguous combination after launch.
Keep production economics separate from checkout discounts
An on-demand store can avoid committing to finished-goods quantities before employees choose, but it does not establish whether a sale price is commercially sustainable. Price the product, decoration, fulfillment and support arrangement actually offered. A discount visible to employees is not evidence that the supplier's underlying costs have changed.
Bulk can be appropriate for a known event quantity or a deliberately purchased stock assortment. A clearance offer may help move that stock, provided the assortment and gift promise remain suitable. Hybrid programs can let employees choose stocked items while keeping other products on demand. In either case, identify which items belong to the promotion rather than applying an unexplained storewide reduction.
When comparing these models, keep one question constant: what does it cost to provide the promised fulfilled selection under the approved policy? Compare real quotes and expected use, not the largest percentage printed on a promo tag.
Explain the outcome in recipient language
For a program that permits approved sale prices, a useful starting point is: “Your company-funded amount applies to eligible merchandise at the price shown at checkout. Approved offers may reduce that price. The checkout will show any remaining amount before you order.” Then add the actual rules for delivery, unused funding and employee payments.
For a dedicated gift selection, say that the invitation provides a choice from the program assortment and explain whether other store offers apply. Do not tell recipients to enter a retail code simply to obtain the fully funded gift already promised. Keep technical words such as discount class out of the invitation; reserve them for the provider's configuration record.
Frequently asked questions
Does “no discount stacking” prevent gift-card payment?
Not necessarily. Shopify explicitly supports using gift cards with discount codes. Verify payment and promotion controls separately on your actual store.
Should employees keep the benefit of a sale?
That is a program decision. You can permit eligible reduced prices, but also specify whether the resulting unused funding carries over. Do not let a checkout default make that promise accidentally.
What happens if a discounted gift is returned?
Use the recorded transaction and approved remedy policy, not the undiscounted list price, to investigate the outcome. Resolve both the payment correction and the employee's remaining gift opportunity through a documented gift-refund and selection-restoration process.
What is the minimum approval standard?
The program owner should be able to explain the eligible price, permitted promotion, employer-funded amount, employee amount due and remaining entitlement for every approved path. If those five answers are unclear, the offer is not ready to launch.